The 12-Slide Pitch Deck Structure Investors Expect (With Examples)
Investors often give a pitch deck only a few minutes before deciding whether to take the meeting. In that time they are not admiring your slides. They are checking whether your story answers their questions in the order they ask them.
This guide walks through the 12-slide pitch deck structure that does exactly that, slide by slide, with what to include, what investors look for and the mistakes that lose the room.
Key takeaways
• Fix the story before you open a design tool. Structure decides whether a deck builds momentum or reads as a list of claims.
• Lead with the problem, not the product or the market size. Investors care about the market only once they feel the pain.
• Each slide should make one point that can be read in about 20 seconds.
• Show real numbers: pricing, unit economics, traction trends and the assumptions behind your projections.
• End with a specific ask tied to milestones, so the investment reads as a plan rather than a request.
Why pitch deck structure matters more than design
Most first-time founders work in the wrong order. They pick a template and start making slides before they have decided what the story is. The result looks polished but does not flow.
Structure decides the order in which an investor meets each piece of information. Done well, each slide answers a question just before it turns into an objection, and makes the next slide more believable.
Design still matters (more on that below). But a clear story with average design beats a beautiful deck with a muddled story, because investors back the story first.
The 12-slide pitch deck structure at a glance
This structure builds on two well-known frameworks: Guy Kawasaki's 10-slide "10/20/30" rule and Sequoia Capital's published guidance on what a pitch should cover. It adds the slides today's investors expect, such as go-to-market and a clear ask.
| # | Slide | Its job | The investor's question |
|---|---|---|---|
| 1 | Title | Name your category in one line | What is this company? |
| 2 | Problem | Make the pain felt | Is this a real, urgent problem? |
| 3 | Solution | Show the insight | Why is this approach better? |
| 4 | Market | Size the opportunity, bottom-up | Is it big enough for a venture-scale company? |
| 5 | Product | Make it tangible | Is it real, and is it good? |
| 6 | Business model | Explain how you make money | Does revenue grow faster than costs? |
| 7 | Traction | Prove something is working | What is the growth trend? |
| 8 | Competition | Define your position | Why can't others copy this? |
| 9 | Go-to-market | Show how you win customers | Can you acquire customers efficiently? |
| 10 | Team | Prove founder-market fit | Why are you the ones to win? |
| 11 | Financials | Show you understand the model | What has to be true for this to work? |
| 12 | The ask | Close with a plan | What do you need, and what will it achieve? |
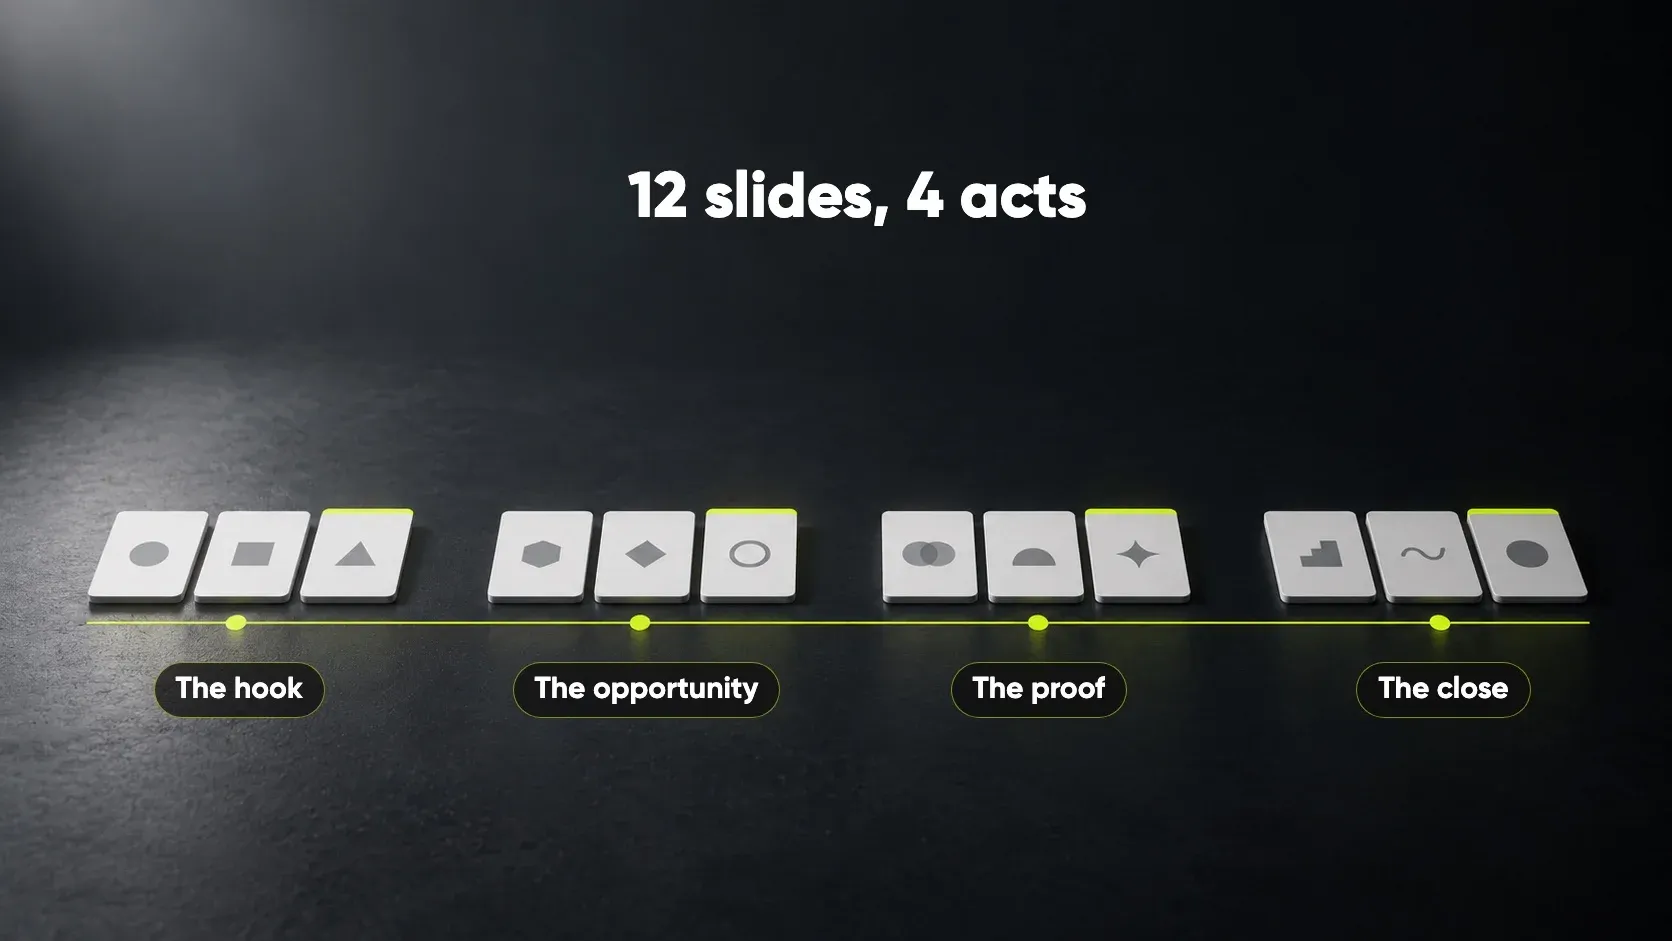
Think of it as four acts of three slides: the hook, the opportunity, the proof and the close.
Slides 1–3: the hook (title, problem, solution)
Slide 1: Title – your category in one line
Include your company name, logo, contact details and a one-line descriptor of under 12 words. The descriptor is what matters. It should tell an investor your category and why it matters, with no head-scratching.
Example: Airbnb's early seed deck opened with "Book rooms with locals, rather than hotels." Uber's early tagline, "Everyone's private driver", did the same job in three words.
Avoid: a tagline in place of a descriptor. "Redefining how the world connects" says nothing. "AI-powered fleet management for last-mile logistics" says everything.
Slide 2: Problem – make the pain impossible to ignore
The investor should feel the problem, not just understand it. Use three lines or fewer:
- The scenario: a real person hitting the problem, in one sentence.
- The root cause: why the problem exists today.
- The cost: what it costs that person in time, money or results.
Investors look for: first-hand understanding. The best problem slides read as if the founder has lived the problem, not researched it.
Avoid: opening with "The global X market is worth $Y billion". Lead with pain, not market size.
Slide 3: Solution – the simplest possible explanation
One job: in about 30 seconds, show what the product does and why it beats the alternatives. Use one sentence describing the product, then three benefits (what the customer gains), not features (what the product does).
Investors look for: an insight, a non-obvious reason your approach is better. Solutions that are obvious rarely attract venture money; ones that seem obvious only in hindsight do.
Example: Dropbox's famous early demo video sold one simple idea: your files, on every device, always in sync. No jargon, instantly clear.
Slides 4–6: the opportunity (market, product, business model)
Slide 4: Market – size it from the bottom up
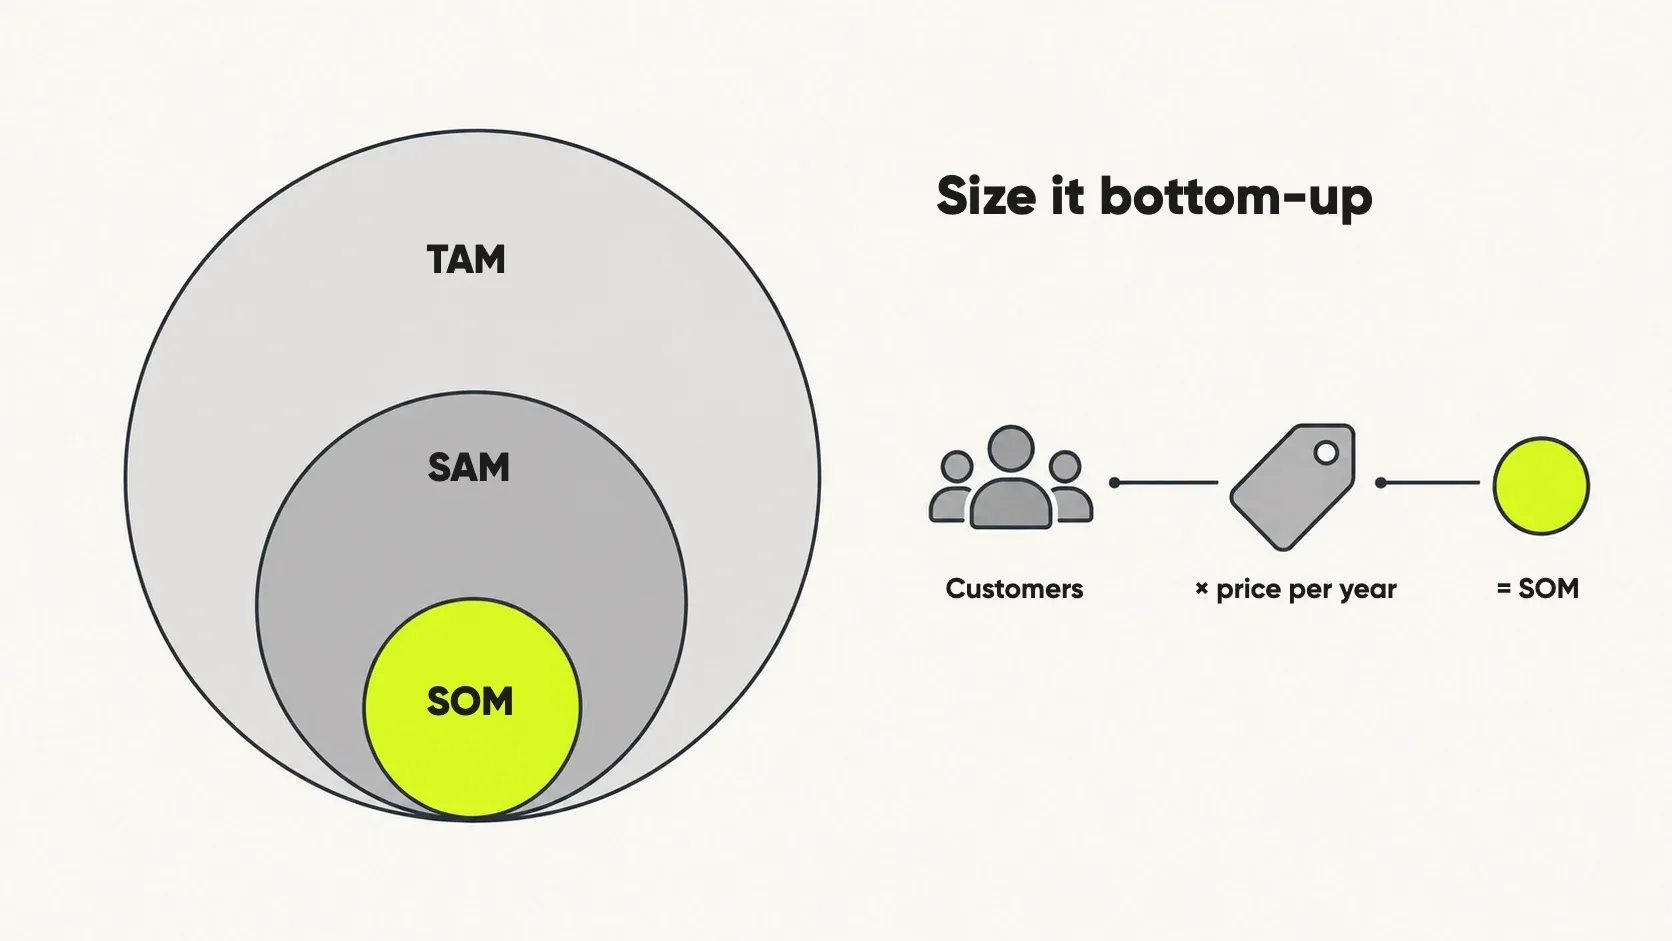
Show three levels. TAM is everyone who could benefit, SAM is the part your current model can reach, and SOM is the share you are targeting within a set time. The SOM is the number investors will hold you to.
How to apply it
- Build the SOM bottom-up: number of target customers × price per year = your realistic market.
- Skip "we only need 1% of a $50B market". Investors dismiss it straight away.
- If you quote an analyst figure, break it down to show how much of it you can actually reach.
Slide 5: Product – show, don't describe
Screenshots, a short demo GIF or high-quality mockups say more about quality and maturity than any bullet point. For pre-product companies, detailed mockups prove the team has thought through the experience, not just the idea.
Avoid: a full-interface screenshot with every menu showing. Show one key workflow, done beautifully. For why the interface itself sells, see why your product UI is your most powerful sales tool.
Slide 6: Business model – how you make money
Cover four things clearly:
- Revenue model: subscription, transaction fee, freemium, marketplace and so on.
- Pricing: real numbers, never "on request".
- Unit economics: a simple view of customer acquisition cost (CAC) and lifetime value (LTV), or margin per transaction.
- Timeline: how soon a typical customer starts paying.
Investors look for: revenue that grows faster than costs. A business where revenue rises only as fast as headcount rarely suits venture capital; software where the tenth customer costs little more to serve than the first does.
Example: Reid Hoffman has published LinkedIn's Series B deck with his own notes. It is a useful read on explaining a business model in terms of network value.
Slides 7–9: the proof (traction, competition, go-to-market)
Slide 7: Traction – the trend, not just the number
Lead with the metric that best reflects your core business health, and show it over time. A rising line says more than a single figure, because it shows trajectory.
- SaaS: ARR or MRR with growth rate.
- Marketplace: gross merchandise value (GMV) and take rate.
- Consumer: daily or monthly active users, with retention cohorts.
Investors look for: signs of product-market fit, meaning customers would really miss you. Retention cohorts and a few specific customer quotes are the strongest early signals.
Avoid: vanity metrics like total sign-ups or downloads. Show 100,000 sign-ups and the first question is "how many are active?" Answer it on the slide.
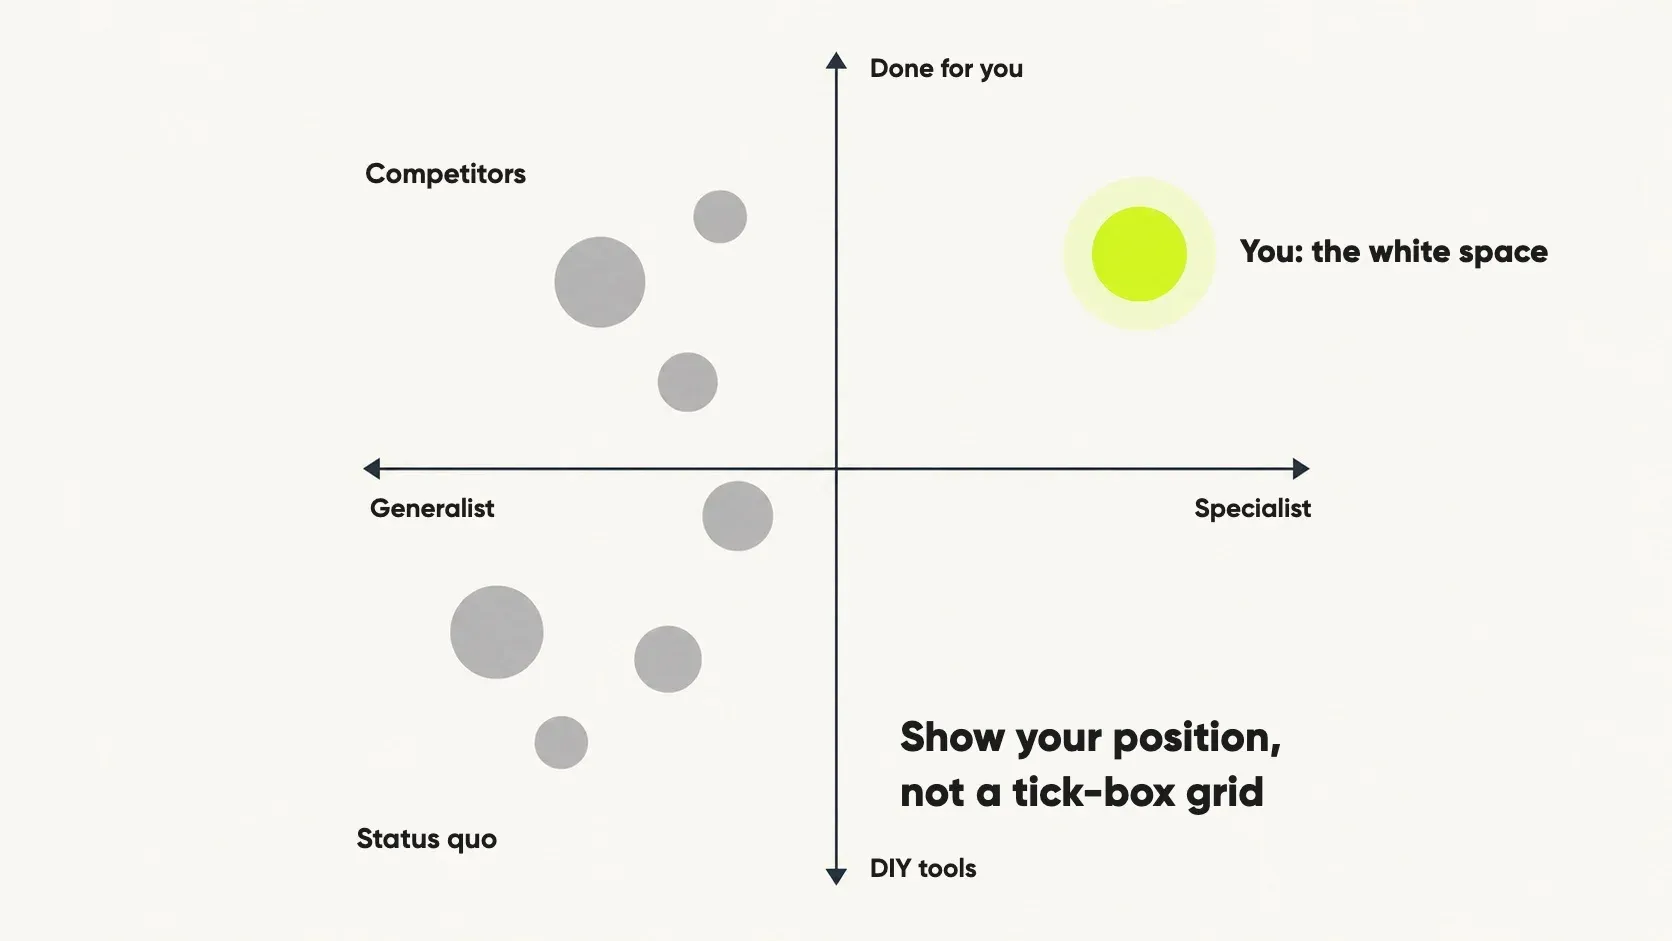
Slide 8: Competition – a position, not a tick-box grid
A feature grid where you tick every box and competitors do not is discounted on sight. Use a two-axis map instead, placing you in a white space no competitor occupies. Your choice of axes shows what you think the market really competes on.
How to apply it
- Name the serious competitors and say honestly what they do well.
- Include the status quo: spreadsheets, manual work or doing nothing.
- State the one thing they cannot do without changing their business model. That is your white space.
Never claim "no competition". It suggests either there is no market or you have not looked.
Slide 9: Go-to-market – one channel, proven
Answer "how do you actually get customers?" Name your main acquisition channel, its numbers (CAC and conversion at each stage) and how customers grow in value after they join, often called land-and-expand.
Investors look for: channel-product fit. Content marketing for a consumer app makes sense; enterprise outbound sales for a low-priced consumer app does not.
Avoid: listing ten channels. It signals you have not found what works. One channel with real data, plus the next one you will open, is far more convincing.
Slides 10–12: the close (team, financials, the ask)
Slide 10: Team – why you are the people to win this
At the early stage, investors are largely backing people. Skip the CV bullets. For each founder, answer one question: why is this person uniquely placed to win in this market?
- Domain expertise: deep knowledge of the customer's world.
- Technical ability: the skills to build the product.
- Distribution advantage: the reach to land the first customers.
The test: if an investor thinks a well-funded rival could hire an equally good team in six months, the slide has not done its job. Show your unfair advantage: relationships, data, know-how or technology others lack.
Slide 11: Financials – a model, not a prediction
Nobody expects early five-year projections to be accurate. Investors are checking whether you understand your business well enough to model it, and whether your assumptions hold up when challenged.
How to apply it
- Show a three-to-five-year revenue chart, key cost drivers and the point of cash-flow breakeven.
- State the key assumptions on the slide, such as monthly customer growth, conversion rate and pricing.
- Use a chart, not a spreadsheet, so the growth curve and breakeven point are easy to see.
Avoid: the unexplained hockey stick, flat for two years and then vertical. Name the trigger, such as a product launch, partnership or new channel, that causes the jump.
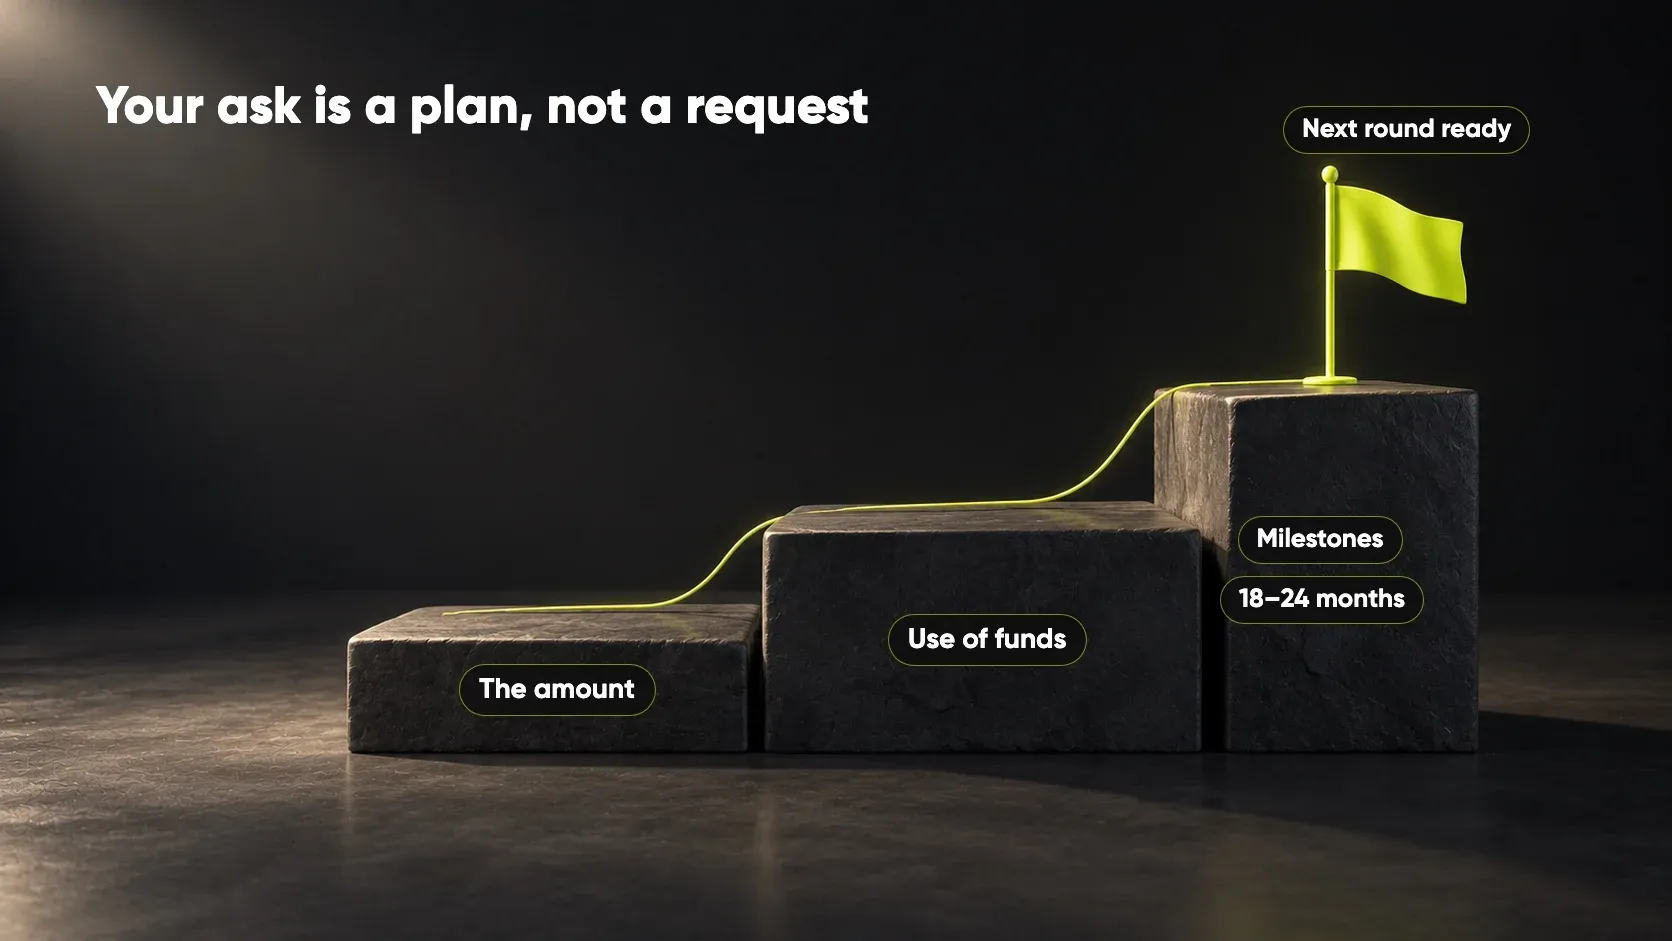
Slide 12: The ask – a number tied to milestones
State three things: how much you are raising, what it will be spent on and what it will achieve. Present it as buying milestones: this money gets us to these specific outcomes, which make the next round straightforward.
- Give 3–5 use-of-funds lines as percentages, for example product 40%, sales and marketing 35%, operations 15%, hiring 10%.
- Name the milestones you will hit in the next 18–24 months.
- Compare "We're raising $2M" with "We're raising $2M to reach $1M ARR and 50 enterprise customers, ready for a Series A." The second gives the investor something to judge.
Avoid: "We're raising a round." That is an opener, not an ask. Come with a number.
4 deck-wide mistakes that lose investors
The slide-specific mistakes are covered above. These four can sink a deck with strong content.
- Slides too dense to read in 20 seconds: one slide, one claim, at most three supporting points. The rest belongs in the appendix or the spoken pitch.
- Solution before problem: without the pain set up first, the investor is judging a feature list rather than a response to a real need.
- Too many slides: twelve is close to the maximum for a first-pass deck. If you need twenty, the story is not clear yet.
- Weak design: uneven fonts, low-quality images and misaligned elements say "low standards" before a word is read. For a product company, that undermines every quality claim you make.
Poor design costs more than most founders think. Our post on the hidden cost of bad design explains why.
The appendix: where everything else goes
Detailed financial models, the full competitor analysis, technical architecture, longer team bios and customer case studies all go in an organised appendix.
It is not a dumping ground. It is what you bring up when an investor's questions show interest in an area, which turns the pitch into a due diligence conversation.
Your pre-send pitch deck checklist
- Does the title slide name your category in under 12 words?
- Does the problem come before the solution, and before any market size figure?
- Is your market sized bottom-up, with a clear SOM?
- Are real prices and unit economics on the business model slide?
- Does traction show a trend over time, plus retention or active use?
- Do you name real competitors, including the status quo?
- Are the assumptions behind your projections visible?
- Does the ask include an amount, use of funds and milestones?
- Can every slide be understood in about 20 seconds?
- Are fonts, colours, images and alignment consistent from slide 1 to 12?
Frequently asked questions
How many slides should a pitch deck have?
For seed to Series A, 10–14 slides is the usual range, and 12 is a common target. Guy Kawasaki's 10/20/30 rule (10 slides, 20 minutes, no font under 30 points) is still a good benchmark. What matters is that every slide answers a real investor question; the appendix can be as long as you need.
Does the pitch deck structure change from seed to Series A?
The 12 slides stay the same, but the evidence changes. At seed, investors mainly back the team, the problem insight and the solution, and traction may be early. At Series A, they expect steady growth, strong retention, improving unit economics and projections based on real acquisition data.
Should I send my deck before the meeting?
Many founders keep two versions. The "send-ahead" deck must stand on its own, with every claim backed on the slide. The meeting deck is simpler and more visual, built to support what you say rather than replace it.
How important is pitch deck design?
Very, but as a trust signal rather than decoration. A clean, consistent deck reads faster and shows you prepare properly. If you are budgeting for help, see how much pitch deck design costs in 2026.
Want a pitch deck investors read to the end?
DesignHQ has been designing for founders and brands since 2016 and has delivered 500+ projects. We help you lock the story first, then design every slide to be read in seconds. You see first concepts within 48 hours, and plans start from $1,500/month.
Explore our pitch deck and presentation design service.